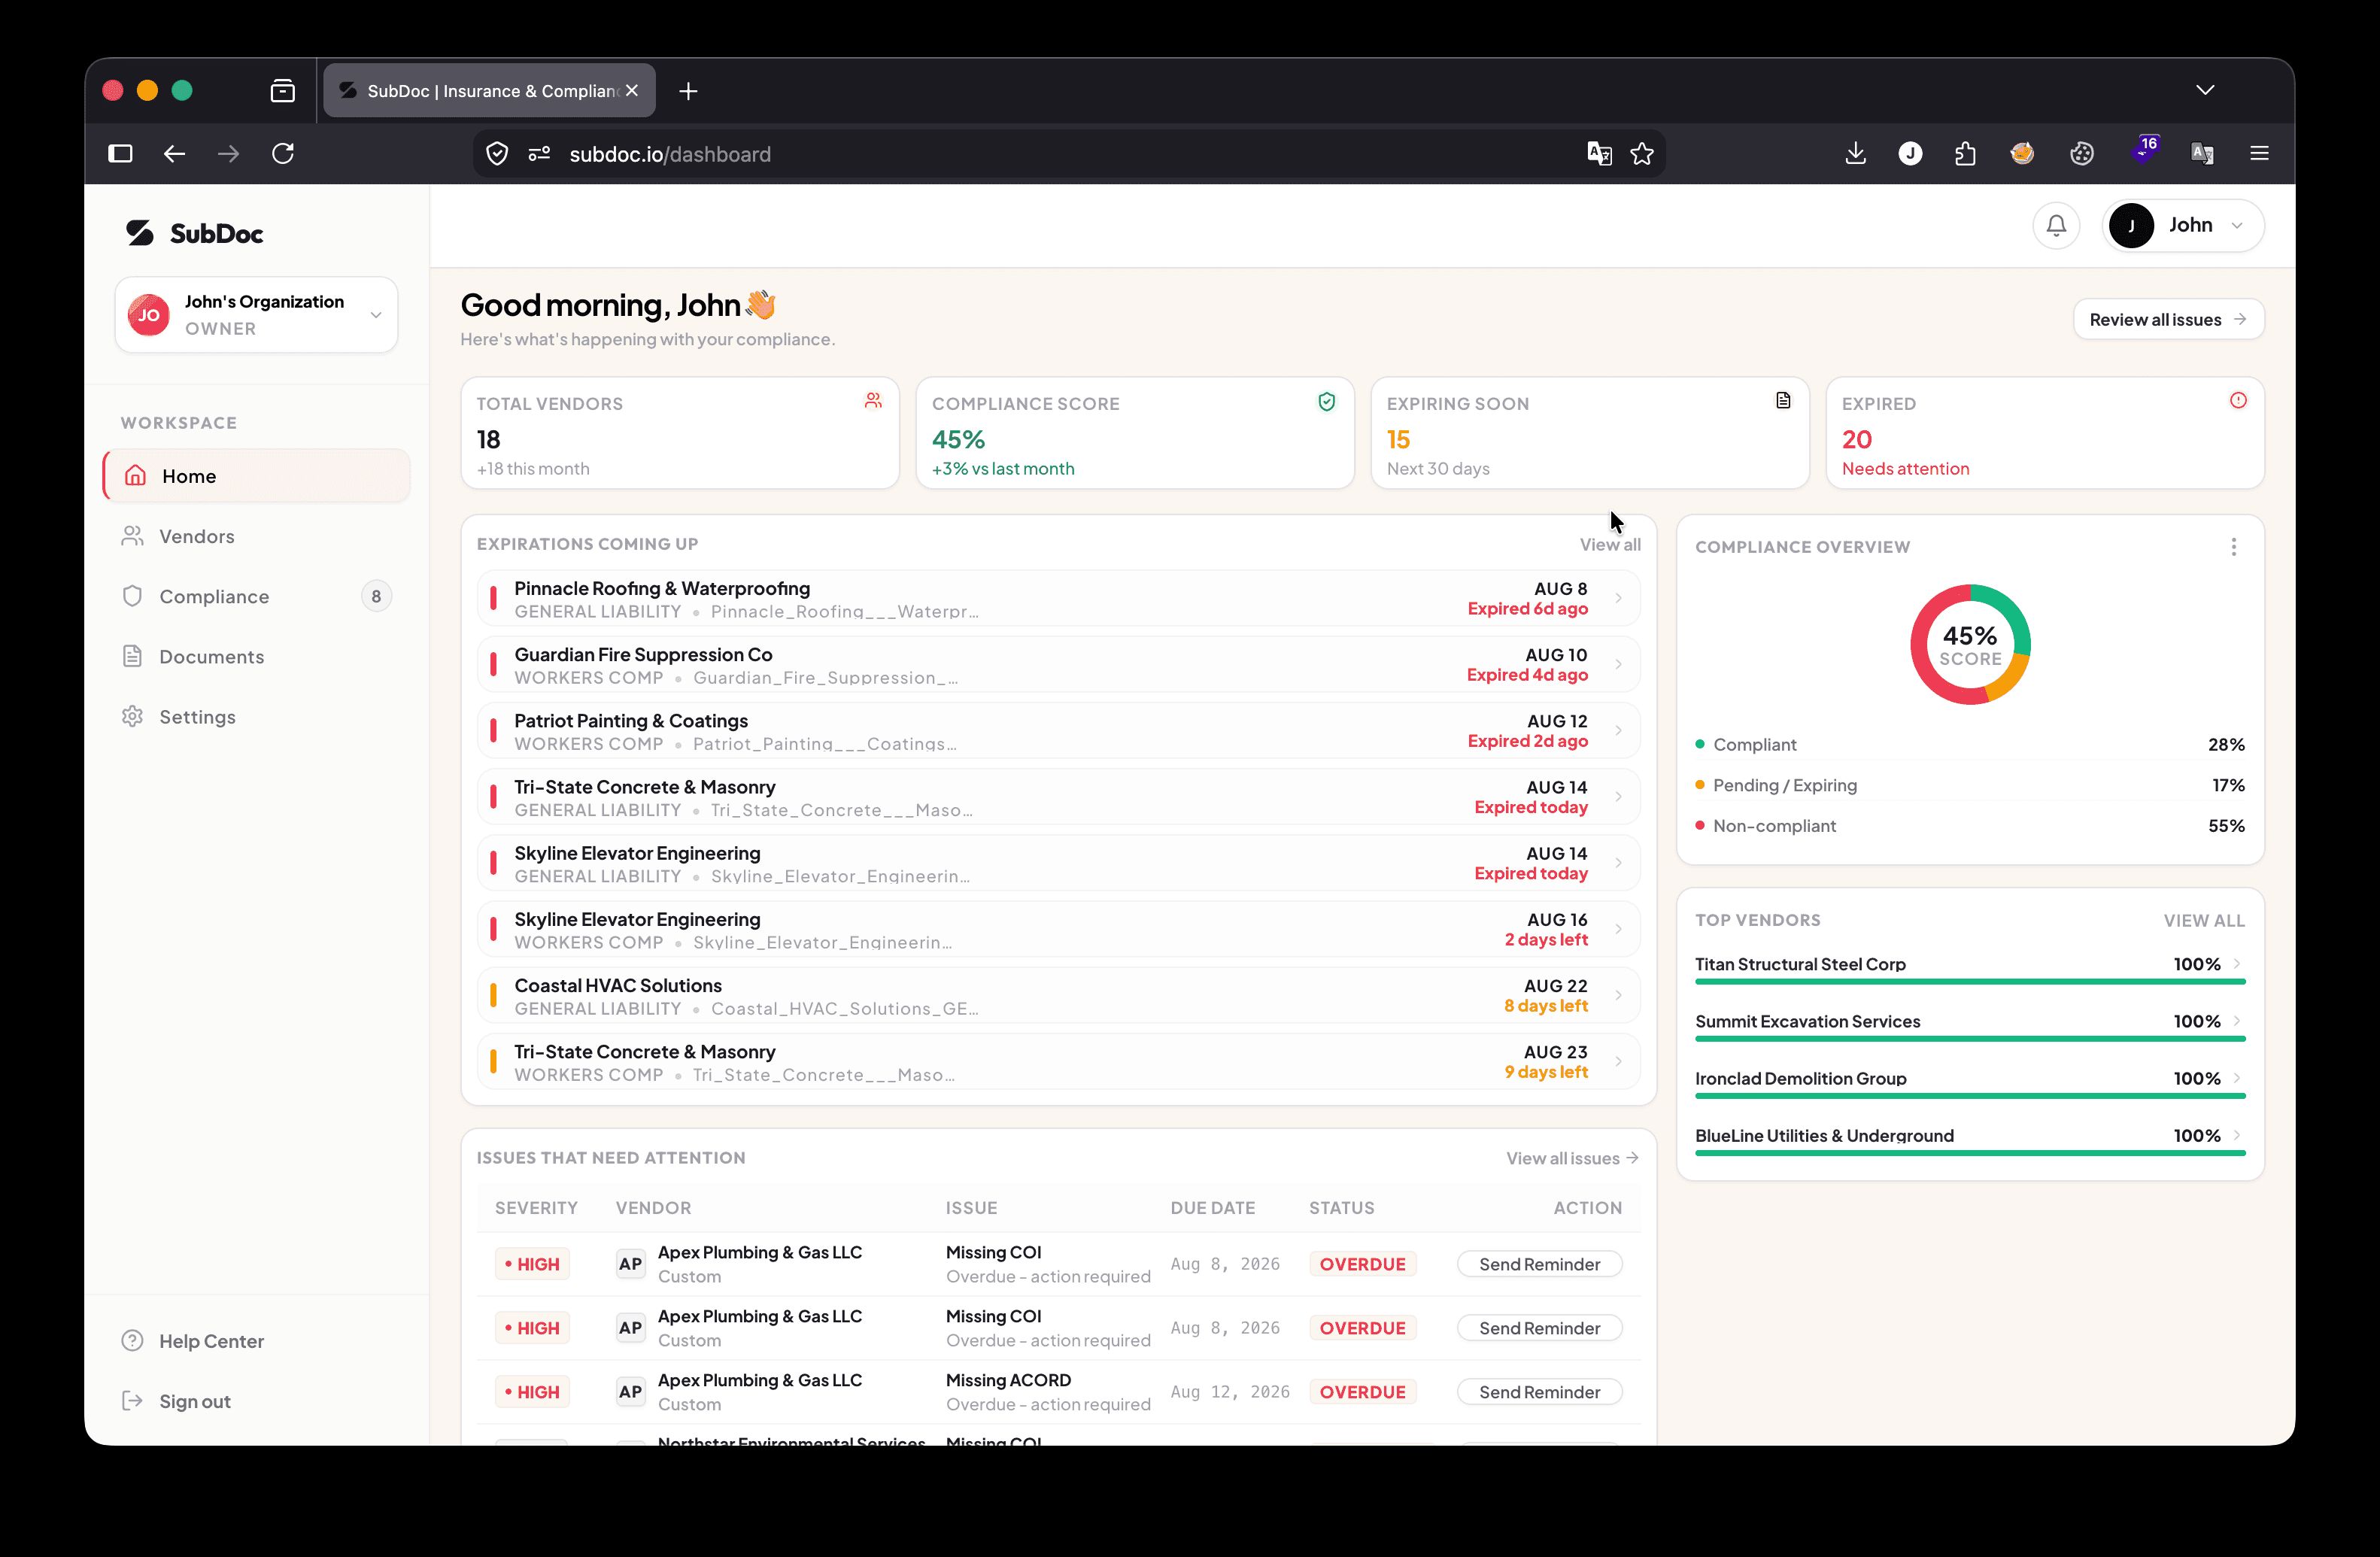
Of construction litigation claims involve expired or unverified subcontractor COIs.
Average back-premium surcharge billed during annual Workers' Comp insurance audits.
Average out-of-pocket loss when a trade worker is injured on site without valid coverage.
Why Spreadsheet COI Tracking Fails at Scale
When managing 5 trade vendors on a single job site, maintaining an Excel spreadsheet for Certificate of Insurance (COI) tracking seems manageable. However, as active sub-traders grow to 20, 50, or 200, manual tracking predictably breaks down due to structural limitations:
- Data Entry Blind Spots: Human errors when typing 10-digit policy numbers or confusing effective dates with expiration dates.
- No Automated Renewal Triggers: Excel cannot automatically email insurance brokers 30 days prior to policy expiration or follow up when ignored.
- Missing PDF Attachment Links: Spreadsheets record numbers but store actual policy PDF files in scattered local folders or email threads.
- Endorsement Oversight: Manual logs fail to verify crucial endorsement forms like ISO CG 20 10 (Ongoing Operations) and ISO CG 20 37 (Completed Operations).
| Feature / Capability | Excel / Manual Logs | SubDoc Automated System |
|---|---|---|
| Document Upload Method | Manual email attachments & downloading | Passwordless vendor upload portal link |
| Data Extraction | Manual typing (100% human dependent) | Instant AI OCR auto-parsing (ACORD 25) |
| Expiration Reminders | Manual calendar entries or missed deadlines | Automated 30/14/7-day email cadences |
| Accounting Sync Alerts | Manual verbal warnings to accounting | Automated status alerts synced to accounting |
| Audit Trail Export | Hours spent searching old email archives | One-click executive audit PDF binder |
ACORD 25 Anatomy: The Field-by-Field Verification Checklist
The standard ACORD 25 (Certificate of Liability Insurance) form is the universally accepted proof of coverage in North America. However, reviewing a certificate requires verifying 6 critical sections:
Named Insured Verification
The name in the INSURED box must match the exact legal entity name on your trade contract. Operating under a DBA or subsidiary without explicit listing voids indemnity protection.
Insurer A.M. Best Ratings
Verify that carrier letters (Insurer A, B, C) correspond to companies with an A.M. Best financial strength rating of A- VII or higher. Unrated carriers pose severe insolvency risks.
General Liability Limits
Standard commercial requirements: $1,000,000 Each Occurrence and $2,000,000 General Aggregate. Crucial check: The "POLICY" or "PROJ" aggregate limit checkbox must be marked "PROJ" (Per Project).
Workers' Comp Statutory Limits
Ensure WC STATUTORY LIMITS is checked. Employer's Liability limits must meet at least $500,000 / $500,000 / $500,000 (or $1,000,000 for high-hazard trades like roofing and steel erection).
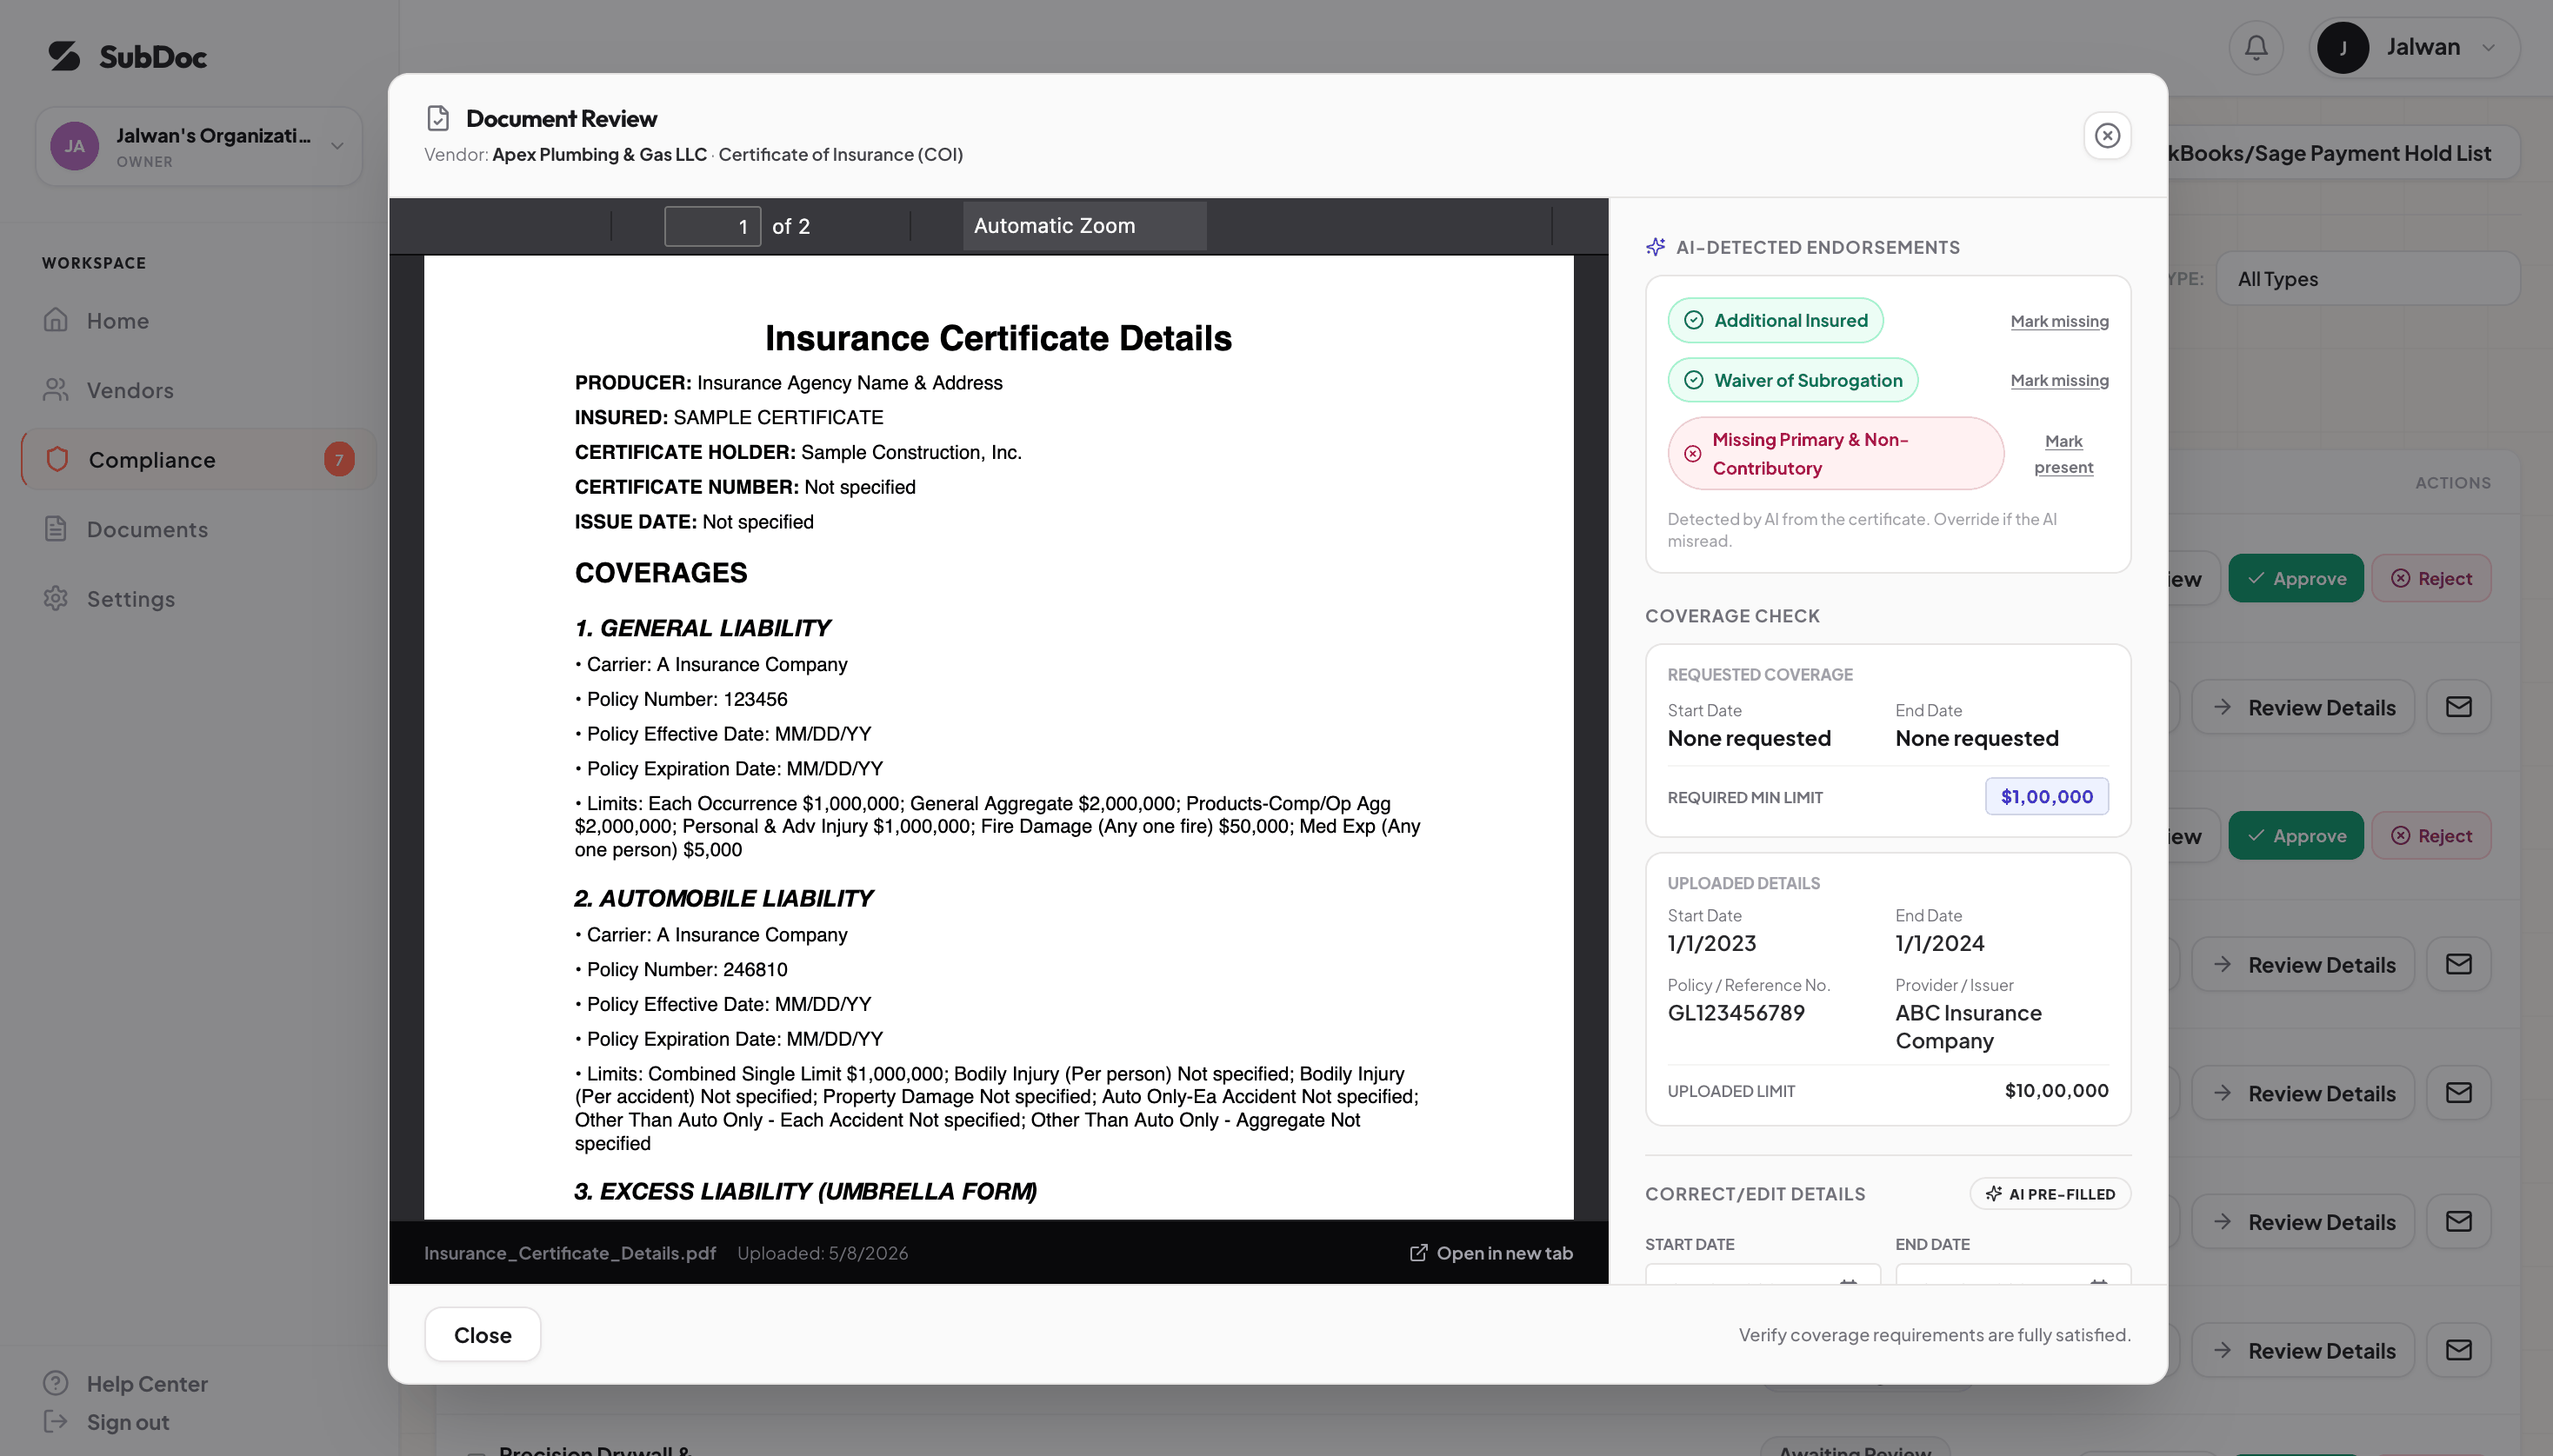
The 3 Mandatory Policy Endorsements You Must Audit
A Certificate of Insurance is only an informational snapshot. Without verifying the attached endorsement pages, your organization has zero guaranteed coverage under the subcontractor's policy:
- Additional Insured Endorsements (ISO CG 20 10 & CG 20 37):
ISO CG 20 10 protects your firm during active construction (Ongoing Operations). ISO CG 20 37 protects your firm against latent defects discovered after the job is completed (Completed Operations). Both forms are required.
- Primary & Non-Contributory Wording (ISO CG 20 01):
Ensures that the subcontractor's insurance pays 100% of a claim first before your own primary insurance policy is required to contribute a single dollar.
- Waiver of Subrogation (ISO CG 24 04):
Waives the insurance carrier's right to seek reimbursement from you after paying out a claim for an injured subcontractor worker on your job site.
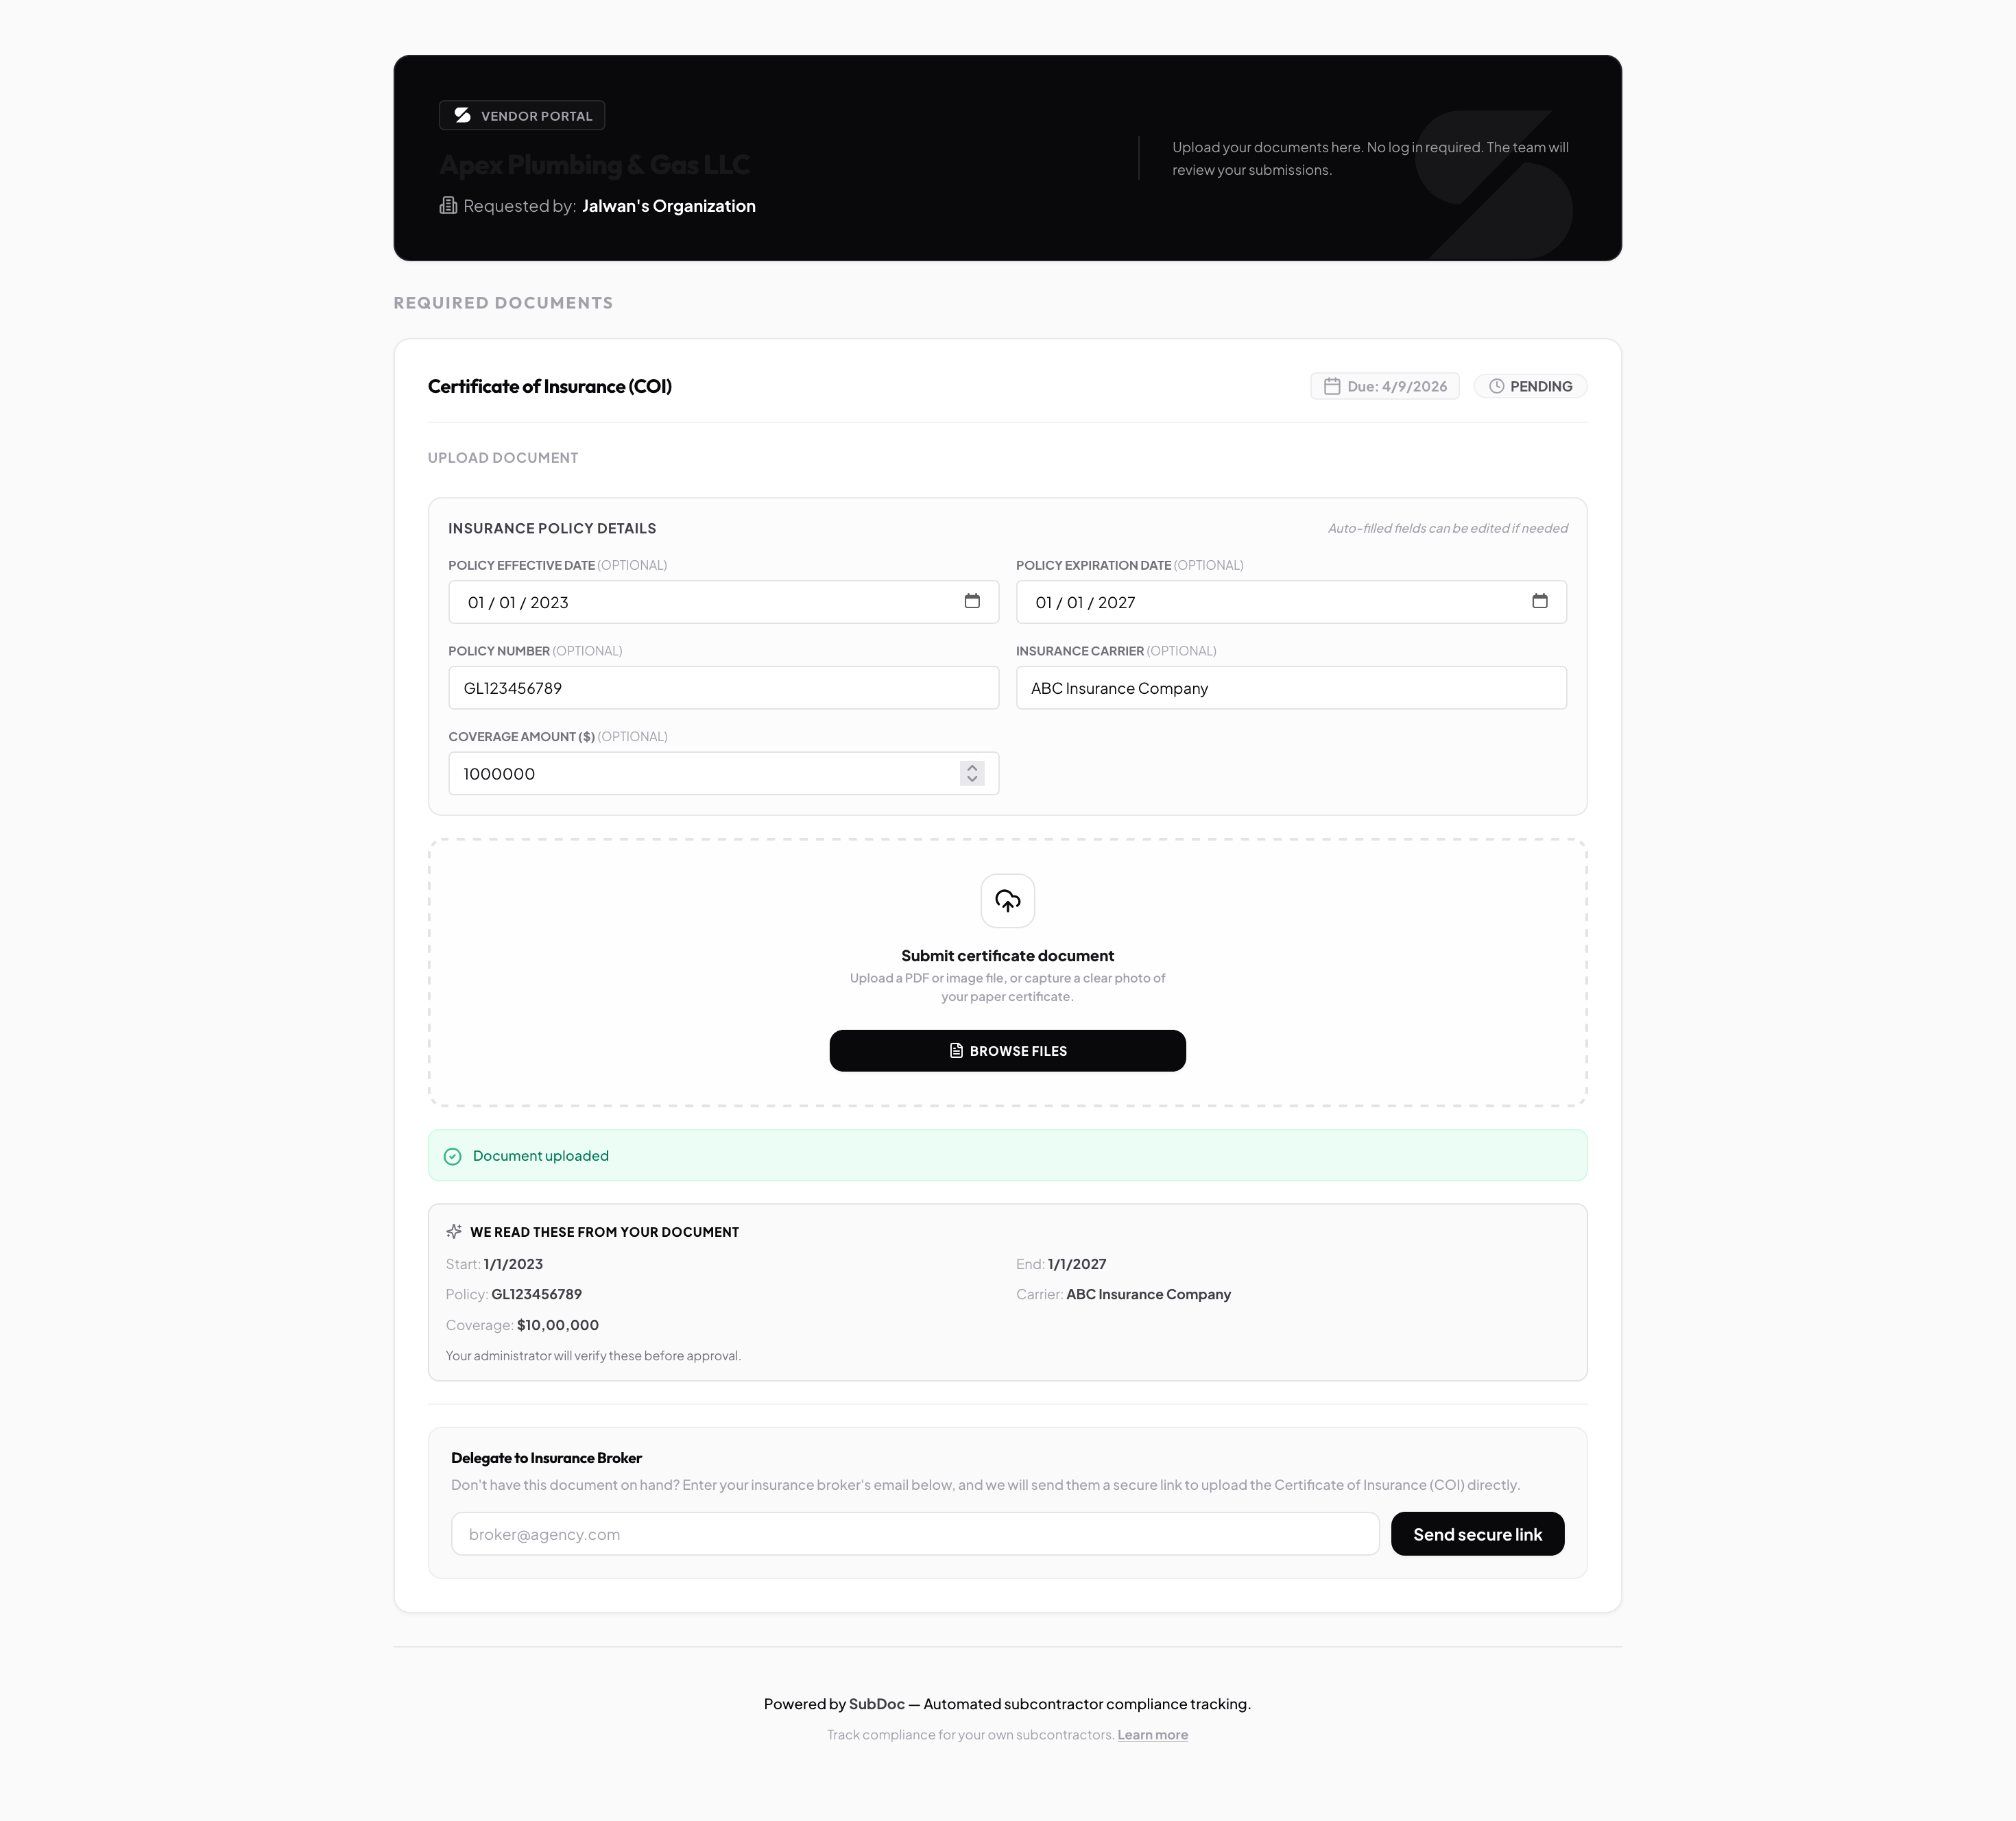
Step-by-Step System: Building an Automated Compliance Workflow
Standardize Master Subcontractor Agreements
Insert strict compliance language into all trade contracts requiring COI submission 10 days prior to site mobilization.
Deploy Passwordless Magic Upload Links
Eliminate login friction by emailing trade contractors a secure 1-click upload link. Vendors can forward the link directly to their insurance broker to attach renewed policy PDFs.
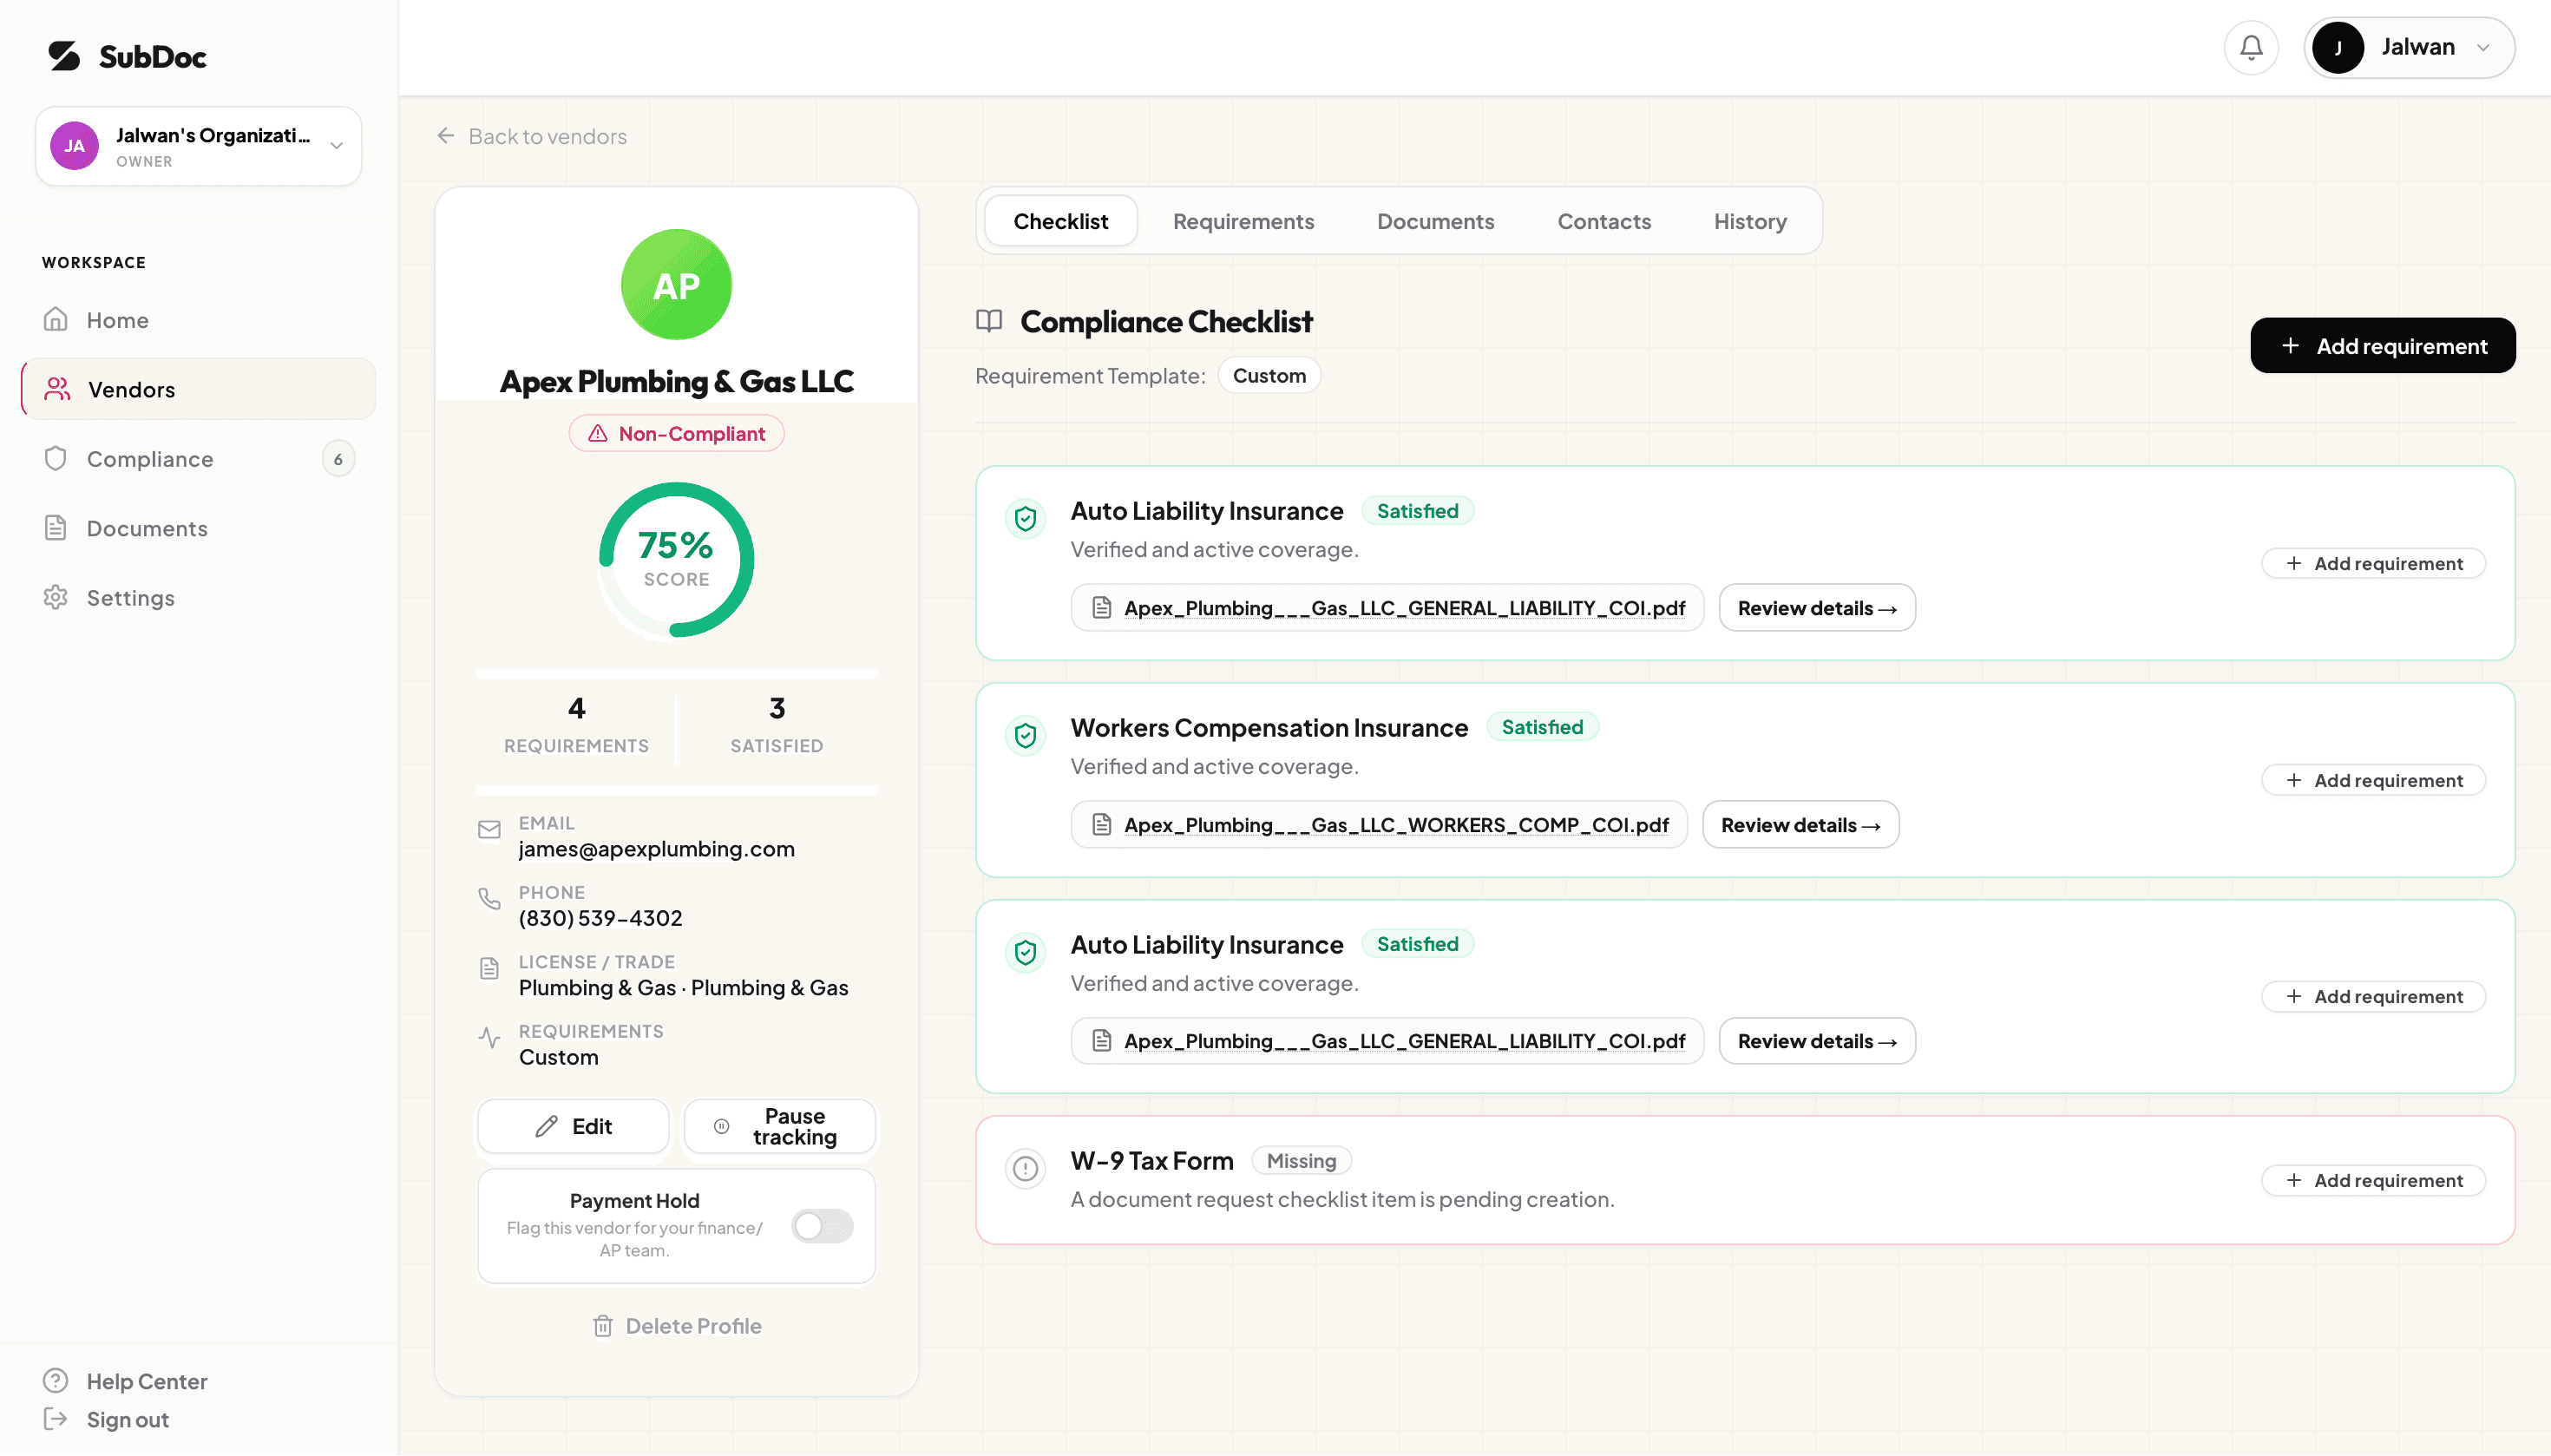
Automate Your Subcontractor COI Compliance Today
SubDoc automates certificate tracking, vendor upload links, and expiration alerts so your job sites stay 100% compliant and audit-ready.