Construction operations checklist
Subcontractor Invoice Approval Process: A Review and Handoff Checklist
Keep work verification, document questions and payment authorization connected by a clear record.
By SubDoc Editorial Team · Published September 30, 2026 · Updated November 12, 2026
A subcontractor invoice approval process should leave a traceable record of what was received, what work was verified, which questions remain open and who authorized the next step. Use separate fields for invoice review and payment status. An invoice marked approved should not be your only evidence that money was released—or that someone had authority to release it.
This is a suggested administrative workflow for construction teams. Payment timing, notices, lien-waiver requirements and remedies depend on the contract, project and applicable law. Have qualified advisers establish those rules before incorporating them into the office checklist.
If the sender needs a starting format, use the free subcontractor invoice template and supporting-document checklist before applying the review workflow below.
1. Record receipt and identify the billing record
Collect invoices through a designated channel and record the actual receipt date, vendor identifier, project, contract reference, invoice number and billed period. Preserve the original submission and its attachments. Assign an internal record identifier so a resubmission can be connected to the earlier version.
Ask the subcontractor to clarify missing identifiers. Do not silently choose a project or legal entity because the company name resembles a familiar vendor. If a document is a progress application rather than a simple invoice, use the billing structure agreed for that contract. Link to the existing payment-application-versus-invoice guide rather than duplicating its explanation here.
2. Check for a possible duplicate
Compare the vendor identifier and invoice reference with the received, revised and paid records. Normalize harmless formatting differences for the search, while preserving the original reference. Also review matching amounts and billing periods when a vendor has resubmitted under a different number.
Treat a match as a review flag, not proof of fraud or authority to delete a record. Determine whether it is an additional bill, a corrected version, a credit or a repeat submission. Attach the explanation to the record and identify which version remains active.
3. Have the project reviewer assess the work
Give the project manager or other designated reviewer the billed work, period, quantities and supporting evidence. Ask for a documented assessment of the amount and work being claimed. A coordinator can collect the material without making the technical assessment on someone else's behalf.
Where the invoice uses a schedule of values, review the relevant lines and adjustments rather than recording only a single overall checkmark. Procore's public subcontractor invoicing description illustrates collection and review against agreed progress milestones or billing cycles. That is the vendor's description, not a claim that SubDoc provides the same workflow or that it guarantees a result.
4. Reconcile contract and billing figures
Keep the original contract amount, approved changes, billed-to-date amounts and payments in distinct fields. Billed and paid are different measures; do not subtract both from the same total without understanding the ledger. Ask the person responsible for the contract to resolve an unsupported change or apparent overbilling.
Use a simple hypothetical review example: a revised commitment is $100,000, earlier approved billing is $60,000, and the new submission requests $45,000. The total being requested is $105,000, so the reviewer needs an explanation of the difference. The example identifies a reconciliation question; it does not decide the payable amount, retention treatment or legal remedy.
5. Route document questions without inventing a payment rule
Check the supporting documents required for this particular billing event. Keep missing evidence, insurance questions and waiver-form questions assigned to the appropriate reviewers. Avoid turning “document outstanding” into an automatic conclusion that every payment can be withheld.
FAR 52.232-27 contains specific subcontractor payment and withholding-notice provisions for contracts to which that federal construction clause applies. It is not a universal rule for all US construction projects. Have counsel identify the applicable requirements, notices and deadlines for the actual job.
For insurance evidence, keep the underlying policy review separate from the invoice approval. Texas's certificate FAQ explains certificate limitations within that jurisdiction. An administrative document flag is not a coverage determination. Refer unresolved insurance-document items to the existing COI exception log, with a named owner and next action.
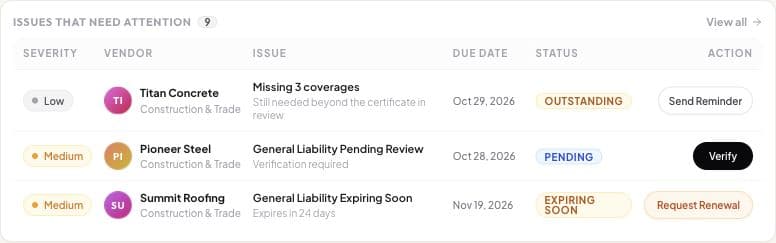
The SubDoc demo issue panel illustrates insurance-document items that need attention. It is not an invoice approval or a record of payment.
6. Record the review decision and communicate the next action
Save the reviewer, timestamp, amount reviewed, referenced evidence and explanation of any requested correction. Identify the active version of a revised invoice. If part of the submission is disputed, ask the authorized person to determine the treatment of disputed and undisputed amounts under the applicable terms; a generic checklist should not decide that question.
Use a clear correction request: identify the invoice, describe the specific discrepancy, state the evidence or correction needed and name the contact for a response. Retain the response with the original record. A workflow status alone does not prove that the subcontractor received the message.
Worked example: review a corrected invoice without counting it twice
On the fictional Alder School project, invoice 214 v1 requests $24,000. The reviewer can tie $21,000 to the base scope, but the remaining $3,000 references a change that the contract reviewer has not confirmed. Record those as two separate review rows. Attach the relevant line or change reference and assign the $3,000 question to the contract reviewer.
When the subcontractor sends invoice 214 v2 for $21,000, compare the changed lines before marking v2 active. Link v1 as superseded and confirm that the original is no longer queued for processing. If it has already been posted, ask accounting to decide how to correct its ledger. Keep the $3,000 change question open in the change register unless the reviewer closes it separately. Record the authorized payment decision against v2.
For a cumulative pay application, compare the new revision with the prior certified application and its supporting schedule. AIA’s G702 and G703 instructions distinguish previous payments, retainage and current amounts requested in that form set. Keep those fields separate if the project uses a cumulative format. See payment application vs. invoice for the two document types.
Download the invoice revision review worksheet (CSV) to record changed lines, evidence, active version and the next reviewer.
7. Keep payment authorization and reconciliation separate
Route the reviewed invoice to the person authorized to schedule and release payment. Record that decision separately from verification of the work. Procore Pay's documentation provides a product-specific example in which different users handle invoice approval and disbursement authorization; it should not be described as a feature of every system or a universal legal requirement.
Verify changes to payment instructions independently. The FBI advises verifying payment requests and account or procedure changes with the person involved; use a known contact channel rather than a new number supplied only in a suspicious message. Do not treat an email signature as the verification record.
After payment, reconcile the payment reference, amount and date to the invoice and approved record. Keep “scheduled,” “released” and “reconciled” distinct where your accounting process uses those stages. Record the actual evidence for each instead of assuming one status means all three occurred.
A practical handoff record
Keep the invoice record ID, vendor and project, original submission reference, active revision, work reviewer and evidence, contract reconciliation, open document questions, correction request and response, authorized payment decision, and reconciliation reference together or linked by reliable identifiers.
This record does not replace a contract, a statutory notice or professional review. Its purpose is to make the administrative handoff understandable to the next person who opens the file.
Explore the SubDoc demo for sample insurance-document views. Check your accounting system separately for the payment workflow you need.